Why Invest in Europe
Some might believe that the overarching real estate dynamics are fairly similar all over the world.
However, a deeper analysis of the two largest markets in the globe (U.S. and Europe) shows a more nuanced picture. The European market stands out with its structural demand drivers and one of the highest supply barriers. In this edition of our “Why invest in …?” series, we will unveil the key features that set the European market apart.
Supply chains are global and similar drivers, such as consumption and manufacturing, fuel the dynamics of logistics real estate.
However, a deeper analysis of the world’s two largest logistics real estate markets reveals differences beneath the surface. In this article, we uncover the unique features of the European market by comparing it to the U.S., which is considered a leading and most mature market globally.
Key learnings:
- Demand in Europe is driven by structural demand drivers: The relationship between economic dynamics and logistics demand is less evident with secular drivers playing a more significant role. This is evidenced by a strong outperformance of occupied logistics stock growth compared to GDP growth.
- High supply barriers keep availability levels low: Access to land and regulatory challenges pose increasing difficulties for many developers, leading to low vacancy rates and a heightened emphasis on Built-to-Suit (BTS) developments compared to the U.S.
- Rent dynamics differ: U.S. has experienced stronger peaks (and troughs), while inflation-adjusted rents remain notably lower in Europe, leaving room for potential expansion.
- Market DNA varies, presenting both opportunities and challenges: The U.S. distinguishes itself with higher institutionalization, transparency, and liquidity, whereas Europe is characterized as a relatively younger market facing supply constraints and placing a strong emphasis on ESG.
Demand propelled by secular tailwinds
Economic expansion supports all real estate sectors, including logistics. However, as seen in Exhibit 1, the growth of occupied stock outperformed real GDP growth significantly in nine European countries in the period 2013-2023. During this period, economic growth was ~14 %, while occupied stock almost doubled. In the U.S., these two metrics are more closely tied. The strong outperformance of logistics growth compared to GDP growth in Europe is due to the importance of structural drivers, creating resilient demand. These structural drivers include rising nearshoring requirements or undersupplied markets.
Note: EU statistic based on national vacancy levels of 9 countries (Deutschland, Frankreich, Vereinigtes Königreich, Niederlande, Polen, Tschechische Republik, Slovakia, Spain and Italy).
European markets are undersupplied in terms of logistics stock.
As it’s illustrated in Exhibit 2. Over time, this adoption rate is rising, creating structural demand. European markets are undersupplied as Pan-European networks and institutionalization of the asset class only emerged in the early 2000s, driven by the Schengen agreements. The U.S. market is more mature, with initial drivers being the development of the interstate highway network in the 1950s. The level of stock per capita across Europe differs as the role in the supply chain (Pan-EU or domestic focus) and maturity differ. Particularly, CEE and Southern European countries are relatively undersupplied. Expectations are that this trend of a rising adoption rate will continue, although it is not expected to reach U.S. levels due to differences in geography and wealth.
Europe has low land availability and higher regulation.
Across Europe, land has become increasingly scarce, particularly in locations close to consumption centres. Even when a developer has acquired a certain land plot, regulation procedures are lengthy and complex. Based on World Bank data, the average time to obtain a construction permit is over 170 days within the 10 countries GARBE is active in. In perspective, the U.S. average is more than half of that (81 days). Particularly, Western European markets have become stricter, fuelled by limited land and NIMBY discussions.
When construction of a new development is underway, Built-to-Suit (BTS) developments are more common in Europe compared to the US. In the U.S., 84 % of completions were labelled as speculative in 2023, while in Europe, the ratio of speculative as a percentage of total construction varied for key logistics markets between 64 % (Italy) and just under 40 % for Benelux and Germany. This lower share is driven by multiple factors, including culture (risk avoidance), market transparency, lengthy development timelines, and constrained markets. Overall, a lower share of speculative space mitigates the risk of markets becoming oversupplied quickly.
Alignment of European vacancy rates
Supply constraints and structural demand drivers have led European market vacancy levels to align with U.S. levels in the last ten years. In 2023, the Pan-European market vacancy increased by ~100bps but remains below 4 %. The U.S. recorded an uptick as well, with vacancy increasing by 210bps to 5.2 %. This increase of market vacancy was driven by recent high development activity and softening occupier sentiment. In the first half of 2024, a minor increase in vacancy is expected in Europe, but at lower levels compared to the U.S. due to lower development volumes and a focus on BTS. A decline in vacancy is expected for both regions in second half 2024 onwards as current construction pipelines are lower.
Note: EU statistic based on national vacancy levels of 9 countries (Deutschland, Frankreich, Vereinigtes Königreich, Niederlande, Polen, Tschechische Republik, Slovakia, Spain and Italy).
Rents trajectories differs, yield movements more aligned
Europe has seen significant rising rents in recent years, but at a later stage of the cycle and at a slower pace compared to the extraordinary levels seen in the U.S., which recorded double-digit growth for a couple of years in a row. Another key difference between Europe and the U.S. is that inflation-adjusted rents (real rents) are still below 2006 levels in many markets. The European average is around minus 10 %, while the U.S. is around plus 45 %. From an investor perspective, this implies there remains significant rent growth potential before markets become overpriced. From an occupier perspective, this means real estate costs don’t account for a higher share in core supply chain costs (fixed costs, including rents, 3-6 % ).
Strong compression and expansion
Cap rates in Europe and the U.S. have seen a fairly comparable trend of strong compression from 2010 to 2022, followed by expansion and stabilization in the last two years. In the long term, the cap rate spread between both regions has narrowed to close to zero, reflecting the rising institutionalization levels in Europe.
‘DNA’ differs, presenting both opportunities and challenges
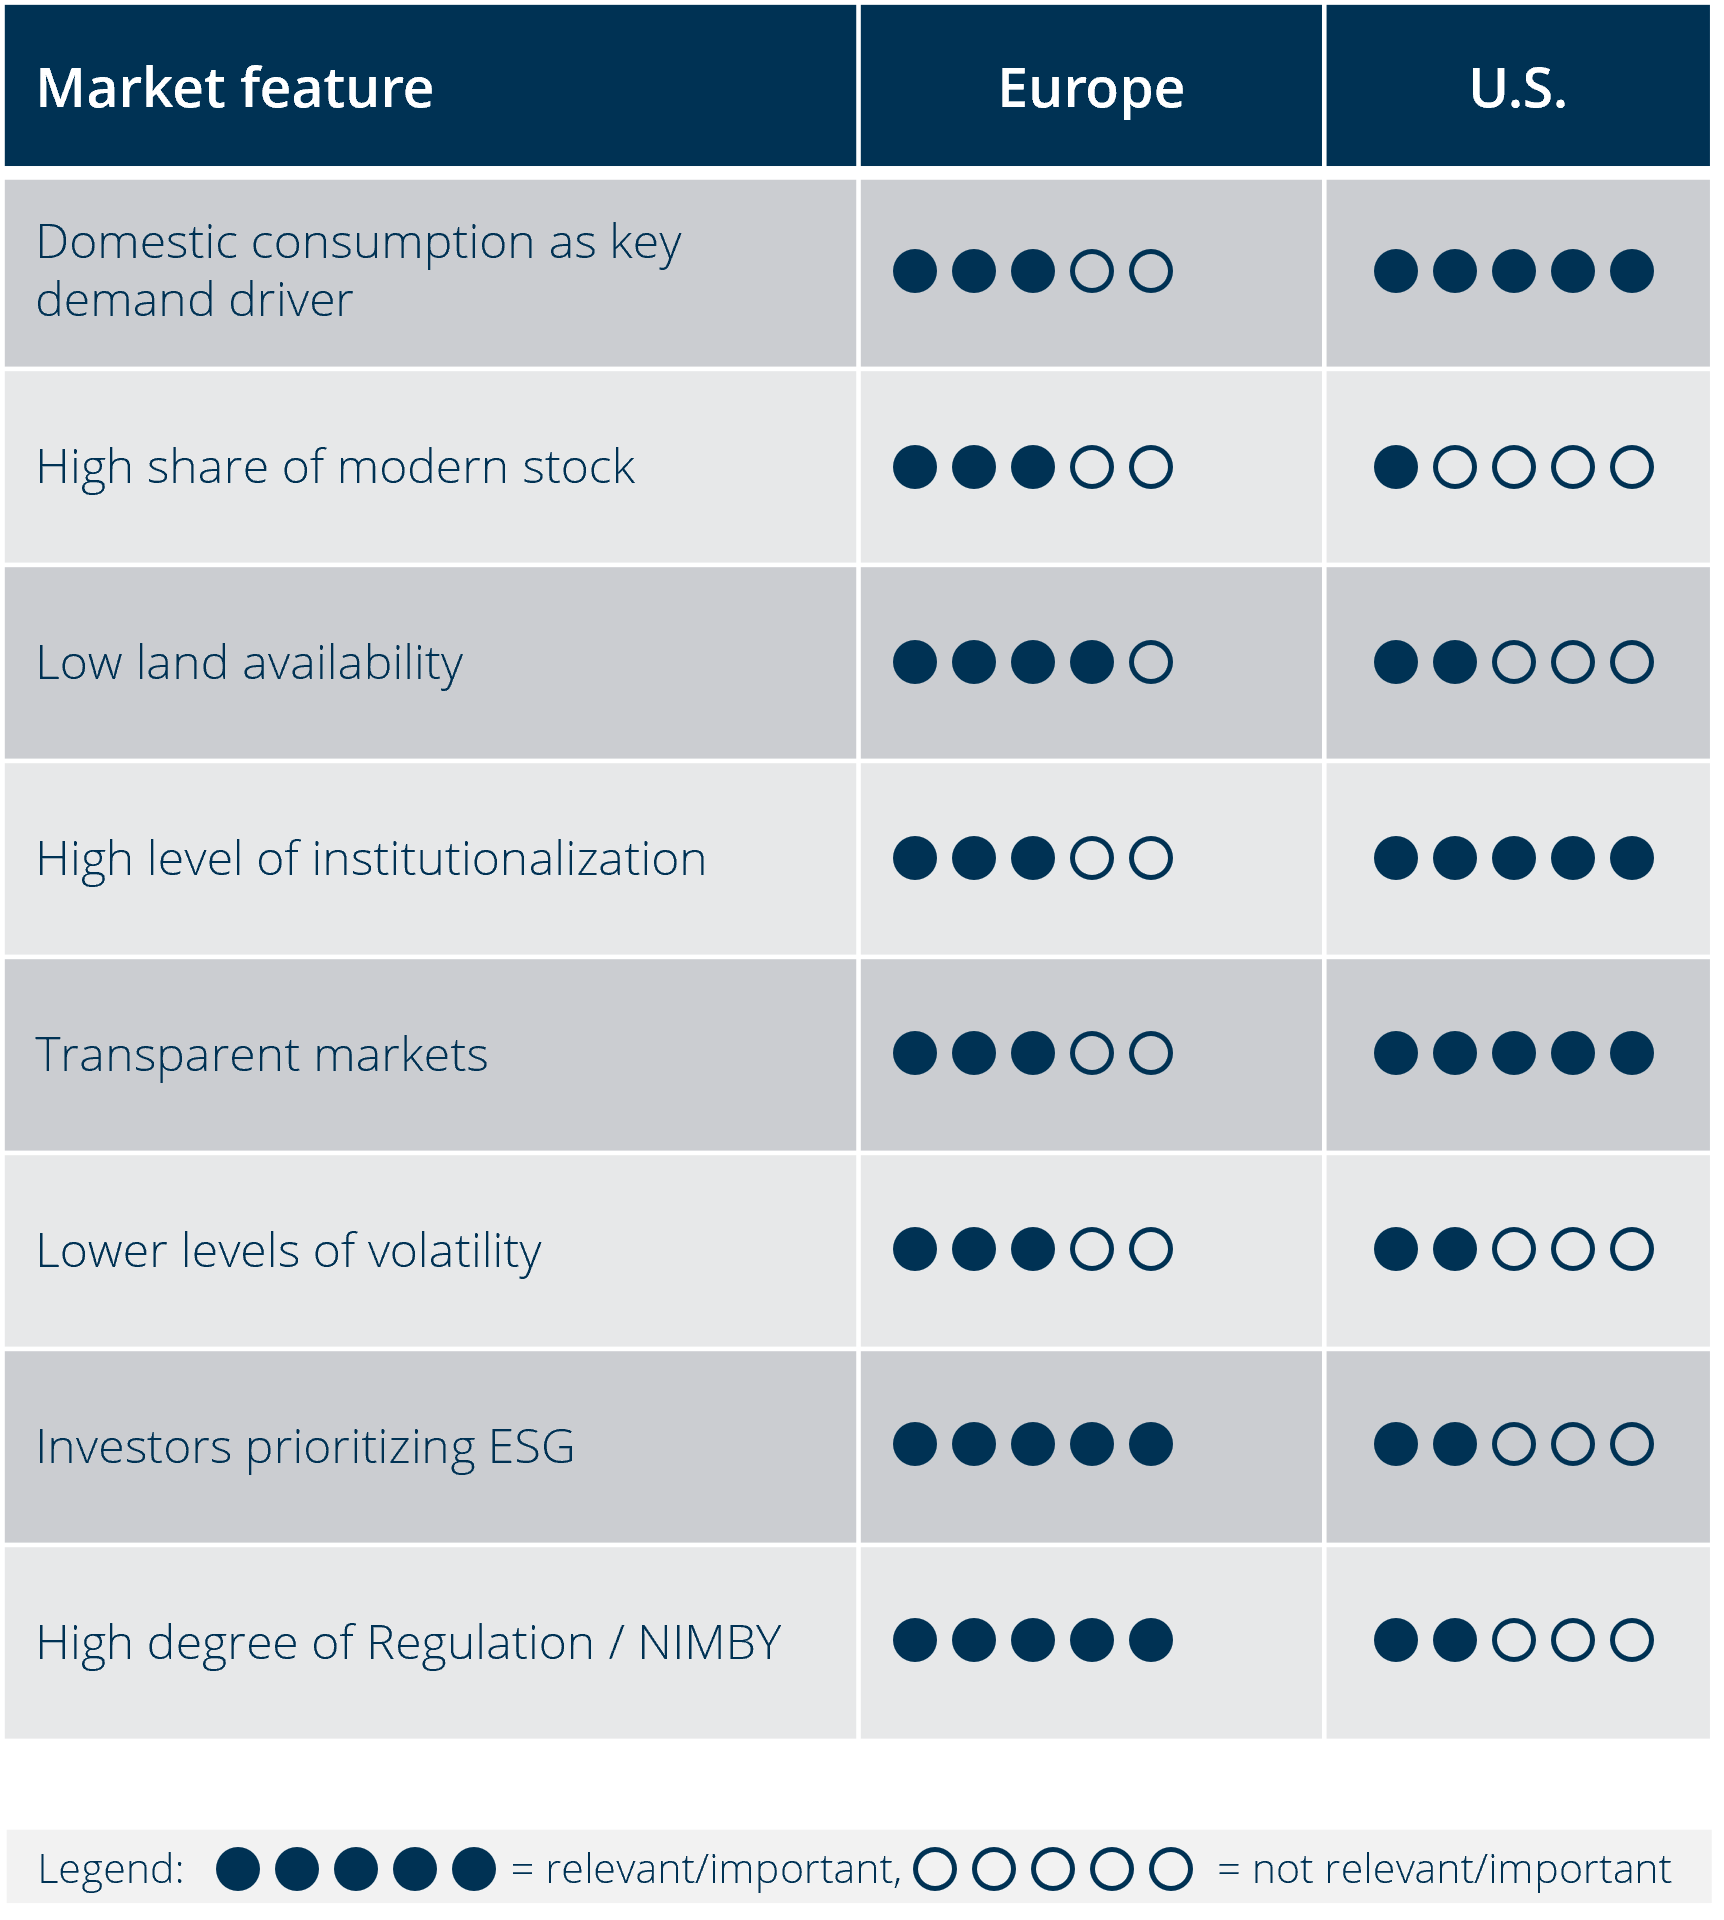
By reviewing a range of market features, it’s clear that the structure of the logistics markets in the two regions differs. Europe stands out in terms of prioritizing ESG and stricter regulation, while the U.S. market is more transparent and institutionalized, but a range of historic KPIs are more volatile.
The comparison between USA & Europe
Europe has historically recorded lower volatility compared to the U.S., particularly concerning rents, capital values, and returns . This is a typical characteristic of the European market, especially for markets on the continent. A relatively stable market is one of the drivers for non-domestic investors to invest in the European logistics real estate market.
Europe is considered a global ESG frontrunner with increased priority among occupiers as well.
ESG is important in the U.S. as well, but the overall consensus is that Europe is further ahead across investors and occupiers.
To conclude, at first glance, logistics buildings and types of locations are fairly comparable in both regions. However, beneath the surface, there is a wide variety of characteristics, offering opportunities and challenges. The European market offers unique and attractive investment features supporting long-term growth.
From a demand perspective, these drivers include undersupplied markets, e-commerce growth in line with pre-pandemic levels and increasing nearshoring activities taking place on the continent. From a supply perspective, rising barriers to new supply and regulatory measures mitigate the risk of oversupply. These supply and demand dynamics support long-term rent growth and continued capital interest. The U.S. market is more mature and has shown strong rental growth in the last decade.